Schedule a free discovery call with a Pension Transfer Specialist
If you’re considering a final salary pension transfer, it’s important to get the basics covered first. So that you understand what it is that you’re dealing with.
We are qualified pension transfer specialists with over 17 years experience with Defined Benefit pensions and we also hold the Pension Transfer Gold Standard which holds us to a higher standard, ensuring you get the best advice available.
This guide is designed to give you basic, generic information, it shouldn't replace tailored financial advice If you'd like to talk about your pension get in touch today and our pension transfer specialists can help you decide what's right for you.
Arrange a Pension Transfer Specialist
No commitment, no hard sales, just a quick chat with one of our pension transfer specialist to see if we can help
What is a final salary pension?
Also known as a Defined Benefit Pension, these are the ‘gold-plated’ pensions you often hear about in the news.
A Defined Benefit Pension or Final Salary Pension guarantees its members a fixed retirement income for life (protected against inflation).
The amount you’ll get is normally calculated on your salary, how long you’ve worked for your employer and a calculation made under the rules of your pension scheme. This amount was often based on your salary at the end of your employment, hence the name ‘final salary’.
Final Salary pension schemes are generally far more generous than their Defined Contribution (Personal Pension) counterparts. In fact, they are often referred to as ‘gold-plated’ pension schemes for this very reason.
The Pension and benefits you will receive are pre-defined by your pension scheme administrators. Whilst each scheme is different in the full range of benefits it offers, members will receive:
- A guaranteed amount of Pension income for life
- Protection against inflation – the amount of money you receive goes up each year, normally in line with inflation. This protects the value of your pension over time.
Other benefits may include
- a protected retirement age,
- a survivor's pension for your Spouse/dependent children if you die (the amount varies by scheme)
- the option to take a cash lump sum on retirement.
Historically you could find Final Salary pension schemes in both the public and private sector, but they have been rapidly disappearing from the private sector with few remaining open to new members.
The rarity and value of these schemes should not be underestimated.
How is a final salary pension calculated?
Each scheme has its own rules that set out the basis of accrual and benefits, but most schemes provide benefits based on 4 key elements:
- The length of the pensionable service you were credited with as being an active member of the scheme i.e. how long you were working for your employer as an active member of your Final Salary pension scheme.
- Your pensionable salary
- The circumstances under which benefits are taken from the scheme (retirement, early payment, early leaver, ill-health, death etc.)
- The formula or rate of ‘accrual’ set by the scheme administrators, which uses service and salary to work out your pension.
Accrual Rates: How do they work?
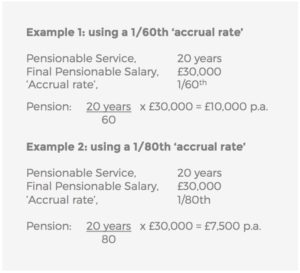
Your accrual rate will depend on the scheme you are in – could be 1/60, 1/80 or some less generous schemes could use 1/125. The example below shows how your accrual rate could affect how much money you get in retirement.
Working out your Cash Equivalent Transfer Value
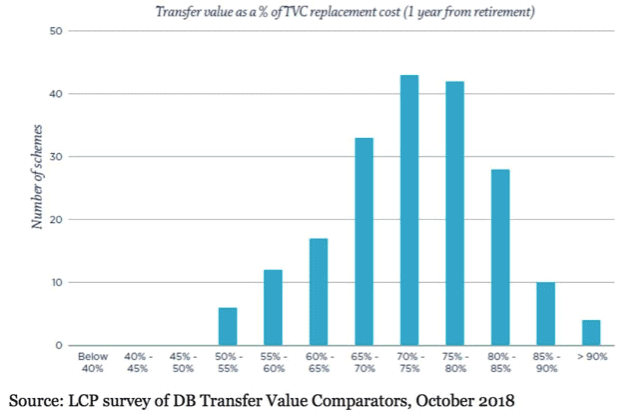
The amount being offered for Final Salary Pension Transfers varies hugely from scheme to scheme with some schemes offering as much as forty times your pensionable income.
Factors that can affect your CETV include
1) Your age at the time of transfer request
2) Your scheme retirement age
3) You pension scheme's funding position
4) The performance of the scheme’s investments
5) Cost of living and inflation rates
6) Life expectancy of the ‘average’ scheme member
It is worth remembering that Pension scheme administrators have the right to adjust pension transfer values to protect the remaining members of the scheme. If too many people are transferring out and it’s threatening the financial health or future of the scheme, they can reduce transfer values accordingly.
If you're trying to work out your Cash Equivalent Transfer Value, some pension schemes will automatically update your CETV on your annual pension statement, in other schemes you will need to request it.
We have developed a Transfer Value calculator that you can use to give you a rough guide of what you could be offered but it is always best to request an estimate from your pensions scheme administrator.
Try our CETV Calculator
Use our simple CETV calculator to see what your transfer value could be
Should I transfer my Final Salary Pension?
For the vast majority or people, the answer to this question is generally, no. Final Salary Pensions provide valuable benefits that will be lost if you transfer out. And these benefits usually cannot be replaced on a like-for-like basis. For most people a Defined Benefit pension transfer is not in their best interests.
That said, whether or not you should transfer is entirely dependent on your individual circumstances and goals. It’s not possible to give you an answer to this question without doing a full analysis of your situation.
As general guidance though there are factors that will make it more or less likely that a transfer would be suitable for you, which you can consider before you explore further.
Questions to ask yourself before you transfer your DB Pension
- Are you married or do you have dependent children?
- Do you have relevant investment experience?
- Are you comfortable with investment risk?
- Is your DB pension a supplementary income source that you could comfortably live without?
- Is your DB pension protected by the PPF?
- Can you achieve your stated goals staying within your existing DB scheme?
Find out why these questions matter below:
Defined benefit pensions don’t just provide a guaranteed income for life for you, DB schemes usually provide a survivor’s pension for your spouse or dependent children.
If you’re not married and you don’t have any dependent children any money you’ve accumulated in your pension gets absorbed back into the pension scheme if you die, regardless of how long you have been taking your pension for.
A pension is generally the largest asset most of us own.
In fact, for over half of married couples, the value of their pensions is worth more than the equity in their home.
Because of this, it's important to understand the gravity of taking on the decisions and risk associated with this kind of investment.
It's not the same as buying some premium bonds or "having a few grand" in a cash ISA.
You'll need to have an investment strategy that is designed to meet your retirement goals that also respects your appetite for risk.
It's a careful balancing act and not for the inexperienced investor
Some people are extremely risk adverse.
This is great if you have a Defined Beneft pension which pays you a guaranteed amount for life in retirement. But not so if you are trying to manage a long-term investment designed to pay you an income through retirement.
Investment risk is par for the course with a defined contribution pension (which is what you'll be moving to if you transfer). You invest your pension pot and it provides you with an income in retirement.
If you're not comfortable with risk then it's unlikely you'll be able to invest in a way that will provide a high enough return to cover your investments fees and beat inflation.
If investment risk is not something you're comfortable with then a DB pension transfer is not for you.
If you cannot afford to live without your defined benefit pension income in retirement then you shouldn't consider transferring.
As soon as you transfer you open the door to investment risk and the value of your pension pot could go down.
Investments can go up as well but it could be a risk that you can't afford to take
Defined Benefit pension schemes in the UK are usually covered by the pension protection fund PPF, which protects Defined Benefit pension members if their pension fund becomes insolvent. It currently protects 90% of the value of members pensions (caps apply) and rises in line with inflation each year. The amount you can receive is capped but the majority of scheme members (99.5%) are not affected by this cap.
If your sole motivation for transferring your Defined Benefit Pension is a concern over the future of your scheme, it’s important to understand if your scheme is covered or not, because if it is, then a transfer for this reason alone is not justifiable.
Find out more about the Pension Protection Fund
This year alone we’ve spoken to several individuals whose sole reason for seeking a transfer was because they were worried that their spouse would not be able to survive on a reduced spouse’s pension (usually 50% of a member’s DB pension).
All were still in the 40s or early 50s with no ill health or reason to believe that they wouldn’t outlive their spouse.
We were able to solve their problem whilst keeping them within the safety and security of their DB pension scheme by simply recommending an appropriate life insurance policy that would cover any shortfall in their spouses income in the event of their untimely death.
This was a relatively low cost solution given the long-term cost and risk of transfer.
Other examples of this include individuals who want to access tax-free cash at 55, who were able to find the money they needed through other investments and cash savings.
Sometimes, all it takes is a quick call with an expert to realise that there are alternative actions available to you.
Other questions to ask include
1) Is there a genuine reason for moving my pension?
2) Will moving my pension allow me to achieve a goal that I couldn’t have achieved otherwise?
3) Would I be able to cope financially without the guaranteed income?
4) Do I understand the true value of the asset and benefits I am giving up, including the future value?
5) Am I comfortable knowing that the value of my pension could fall?
6) Do I have a spouse who would need a guaranteed income if I were to die early?
7) Am I confident I have access to the right investment and pension advice?
8) Do I have a plan to manage my money in a personal pension arrangement that protects the value of my pension and ensures I’ll have an income for life.
It’s important to take a holistic view of your situation before you consider cashing in your pension. It’s easy to let a high transfer value distract you from the difficult questions that need to be answered.
It’s always important to explore whether an alternative course of action could help you achieve your goals first, without you needing to give up your valuable guaranteed income and protected benefits.
Reasons you might want to transfer
Whilst Defined Benefit pensions are highly valued (and valuable) due to their guaranteed benefits, they are, by their nature, inflexible, especially when compared to the flexibility offered by Defined Contribution pensions.
There are 6 main reasons you might consider transferring your Final Salary Pension

A high transfer value
Potential to access a larger tax-free lump sum
Flexibility to access drawdown from 55
Early retirement
Passing on wealth when you die*
Ill health
Tax-planning
*It’s worth noting that Defined Contribution Pensions and SIPPs can usually be passed on free of Inheritance tax to named beneficiaries. find out what happens to Defined Benefit Pensions when you die
Final salary transfer benefits explained
Wondering Is it worth transferring a final salary pension? We've explained the main benefits below:
A high transfer value on its own isn’t a good enough reason to transfer, but transfer values have soared to such a rate that what may not have been possible previously is now made possible by the increase in value.
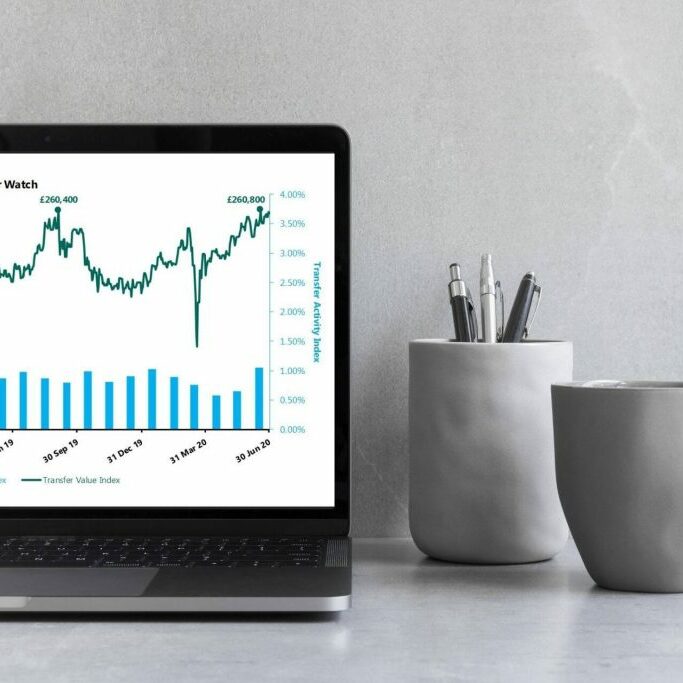
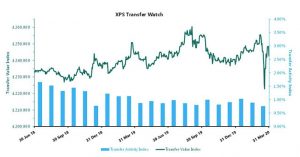
July 2020 saw transfer values reach their highest recorded level and the lure of a high transfer value is too great for some.
Most people we’ve spoken to are in the enviable position that their Defined Benefit pension is surplus to their retirement income requirements, so they’d rather transfer it and have access to it as a lump sum.
Further reading_ Why are pension transfer values so high?
April 2021 will mark 5 years since changes to pension legislation allowed private pension holders to access a 25% tax-free cash lump sum from their pension from 55.
It’s easy to work out 25% from a defined contribution pension, it’s just 25% of the value of your pot. Defined benefit pensions are different, because the ‘pot’ is a theoretical amount (since they’re guaranteed to pay out until you die).
For a selected few schemes, the lump sum is automatically offered in addition to your guaranteed pension income. More commonly this lump sum is offered at the cost of receiving a smaller starting pension, this is known as commutation. The bigger the lump sum you withdraw, the more future pension you sacrifice – and the reductions can be significant.
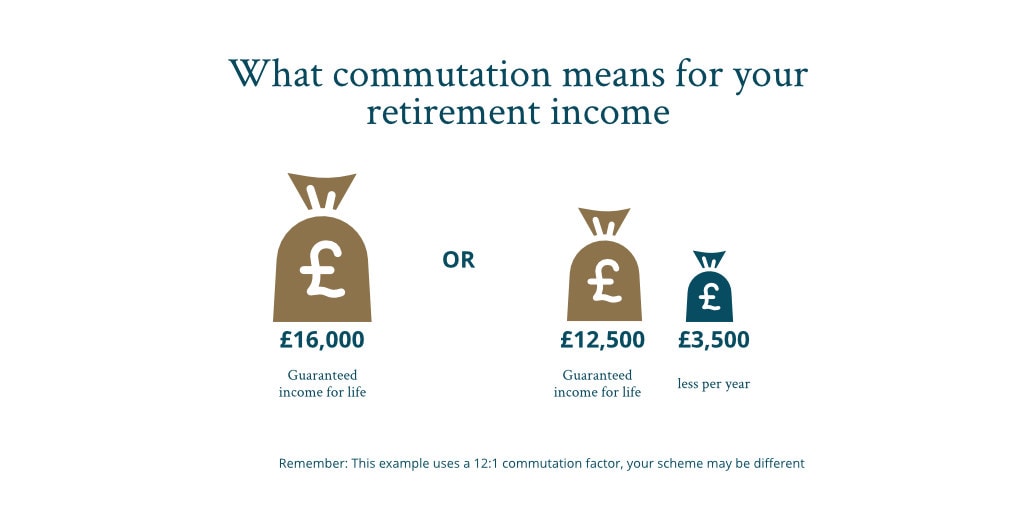
As with pension benefits, the commutation factor will vary from scheme to scheme. For example, a 12:1 commutation factor will mean a £1 reduction in pension for every £12 of tax-free cash.
Lump Sum Commutation Example:
- Jude has a Final Salary Pension worth £16,000 a year.
- Her scheme uses a commutation factor of 12:1 to calculate her cash lump sum.
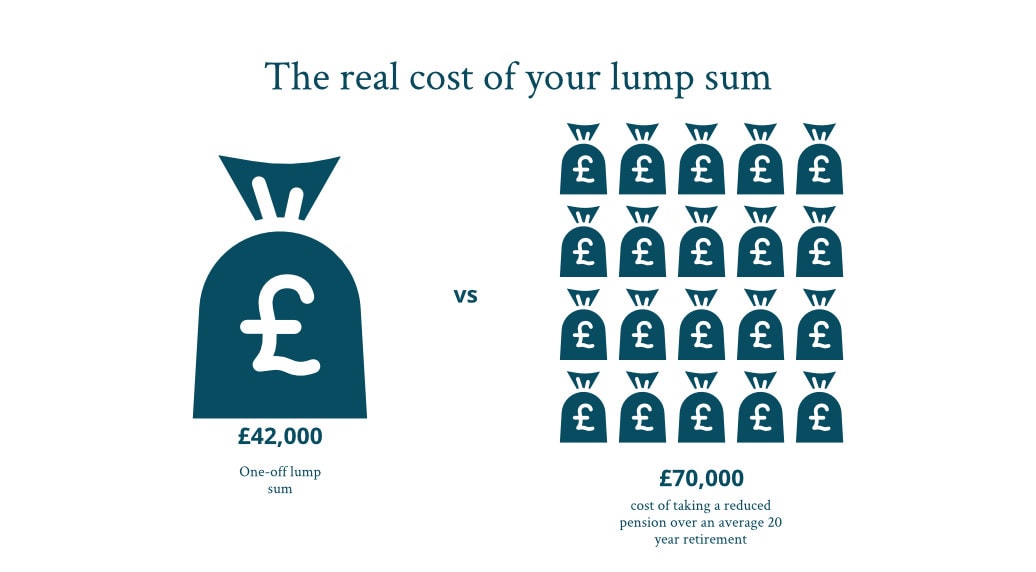
- She opts to take a £42,000 cash lump sum and a lower starting pension of £12,500 (a reduction of £3,500 per year), reasoning that she wants to pay off the remainder of her mortgage early.
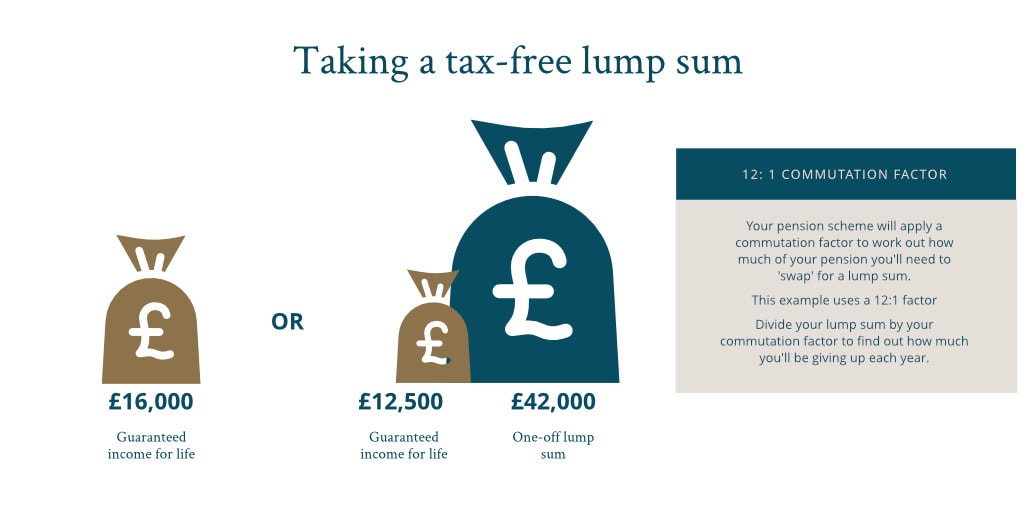
Using a 12:1 commutaion factor to work out a tax-free cash lump sum: 42,000 / 12 = £3,500
If she retires at 65 and has an average 20 year retirement, she’ll have given up £70,000 of pensionable income (20 years of receiving £3,500 less) for her initial £42,000 lump sum (in today’s money).
It’s important to remember that once you have selected your choice of pension benefits, you cannot change your mind in later years. It’s crucial to get the right advice before you make a decision.
This is where you really need advice from a Pension specialist to decide if you might be better taking more as income and less as tax-free cash or leaving it in your Pension Fund.
Pension drawdown enables you to use your pension pot as you wish from the age of55.
Unlike a defined benefit pension or annuity with a flexi-access drawdown you can, as the name suggests, access it flexibly. Which means you can take as much or as little as you want as often as you like, or not at all.
Pension drawdown isn’t for everyone; it’s crucial that you have the plans in place and the know-how to ensure your money actually lasts.
Because once it’s gone, it’s gone. Unlike an annuity or a Defined Benefit Pension, a drawdown pension is not guaranteed for life. So, you will need to manage your money meticulously to make sure it doesn’t disappear.
However, get it right and pension drawdown has some pretty impressive benefits:
- It’s flexible - you can take more when you need it and less when you don’t
- It allows you to manage your withdrawals tax-efficiently
- You may be able to defer paying Life Allowance tax until you are 75
- You can pass any leftover money onto beneficiaries, fully free of inheritance tax
When planning for pension drawdown, you will want to consider the impact on your income if you:
- Live longer than you have planned for
- Withdraw too much money in the early years of retirement
- Invest in funds that don’t perform as well as you had anticipated
Final Salary Schemes normally have a fixed retirement age, so if you’re planning on retiring early this might throw a spanner in the works.
Early retirement might be possible but you’ll need to check whether there are penalties for doing so.
You will normally have to sacrifice a certain amount for every year you are below the fixed retirement age and you’ll also need permission from the Pension Trustees/your employer to retire early.
Some schemes (not all) have a Protected Pension Age, which may allow you to retire early. It’s best to check with the Pension Scheme Administrator to find out exactly what benefits you have attached to your Pension.
Once you start taking your defined benefit pension you’ll receive the same guaranteed amount every year, even if ill health reduces your life expectancy .
If you die early your Spouse will continue to receive a guaranteed income but at a reduced rate (depending on the scheme rules). Any pension income is taxable and your spouse cannot pass on that benefit when they die.
If you were to transfer to a defined contribution scheme then you have a couple of options: you could take advantage of an enhanced annuity which could provide an increased guaranteed income for those with ill health
Alternatively, if you want to prioritise leaving money to your beneficiaries on death, you could transfer your pension to a defined contribution arrangement and take advantage of the inheritance rules surrounding personal pensions.
Whatever the reason, your health could have a bearing on whether or not a transfer is in your best interests.
Defined benefit pensions are guaranteed for life, but what happens when you die?
They usually continue to pay a reduced survivor's pension to your spouse or dependent children, usually 50%.
If you’d rather leave your pension to someone else; grown up children, a family member or a charity, you’re stuck. The rules don’t allow for that. So you’re left with 2 options;
- purchase a life insurance policy or
- transfer your pension to a defined contribution pension where the rules are different and you can leave your pension to whomever you choose.
Defined Benefit pensions and ill health
Once you start taking your defined benefit pension you’ll receive the same guaranteed amount every year, even if ill health reduces your life expectancy.
If you die early your Spouse will continue to receive a guaranteed income but at a reduced rate (depending on the scheme rules). Any pension income is taxable and your spouse cannot pass on that benefit when they die.
If you were to transfer to a defined contribution scheme then you have a couple of options: you could take advantage of an enhanced annuity which could provide an increased guaranteed income for those with ill health
Alternatively, if you want to prioritise leaving money to your beneficiaries on death, you could transfer your pension to a defined contribution arrangement and take advantage of the inheritance rules surrounding personal pensions.
Whatever the reason, your health could have a bearing on whether or not a transfer is in your best interests.
Having a guaranteed amount of money land in your bank account every month isn't normally considered a bad thing, but if you are trying to balance your tax liabilities, you don’t have the flexibility to take less (or more) at any given time.
You may especially find this a restriction if you find yourself over the Lifetime Allowance amount.
If your Pension is over the Lifetime Allowance (LTA) your Pension Scheme Administrators will deduct the additional tax at source from your pensionable income, they’ll adjust the amount as soon as your pension becomes payable.
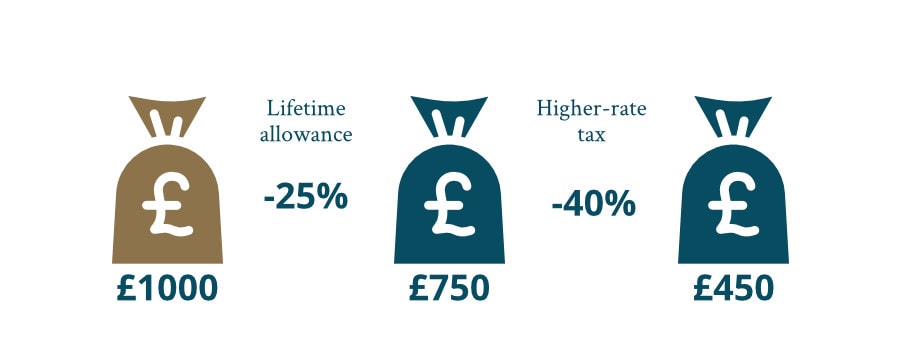
Under defined contribution arrangements, current tax rules allow wealthy individuals using Flexible Drawdown to defer the Lifetime Allowance Tax until they are 75.
By keeping income drawings within the LTA limits up to age 75 (and gaining the benefit of a largely tax-exempt investment account until that date), you can defer paying the lifetime tax surcharge on the value of your pension fund until you are 75.
More on this here…Lifetime allowance and Final Salary Pensions
If you have no need for the funds in excess of the LTA then you could consider leaving these invested in your pension. Although you will eventually have to pay the LTA charge at age 75, the funds will remain outside of your estate and won’t be subject to Inheritance tax.
Arrange a virtual coffee with an expert
No fees, no commitment, no hard sales, just a quick chat with one of our experts to see if we can help
Final Salary pension transfer risks
The general advice for transferring your Final Salary Pension is – don’t, and for good reason.
Choosing to move a Final Salary Pension is an irrevocable decision, so even if the benefits of a Final Salary Pension Transfer appeal to you, you must also seriously consider the risks involved before making your decision:
The risks of pension transfer include:

Running out of money in retirement
Investment risk
Stress of managing your money
Triggering the Lifetime Allowance Tax
Loss of spouse's pension
Loss of inflation protection
With a final salary pension scheme you are paid a guaranteed, fixed amount, every year until your death (or the death of a qualifying financial dependent (if later).
According to the Office for National Statistics, a 65-year-old man has an average life expectancy of 86 (21 years), while a 65-year-old woman could expect to live to 89 (24 years). With one in four 65-year-olds today expected to live to 94 (men) and 96 (women), this makes a final salary pension a reassuring financial prospect.
A personal pension may offer flexibility, allowing you to take out varying amounts from your pension year on year, but once that money has run out, it’s gone.
It is therefore imperative with a personal pension to make a long-term financial plan and manage your money wisely.
You will need to consider such things as life expectancy, your lifestyle, and any financial dependents you may have.
Your plan should be one that will support you for as long as you need, most likely the rest of your life. So, it is reasonable to expect this to last 30+ years.
You may also need to make allowances for the fact you might live longer than you thought!
Couples also need to remember that an income will be required throughout both of your lives.
Find out what your average life expectancy is based on your age and sex using the ONS life expectancy calculator. You’ll also be able to see what are the chances of you reaching 100.
Our Pension Specialists use decumulation calculators to show individuals how long their pension will last at a proposed rate of withdrawal, so you can see, based on your average life expectancy how much you can afford to withdraw from a personal pension.
Of course, you could always outlive your average expectancy.
Remember, a Final Salary Pension pays out a guaranteed amount for life, regardless of what age you live to.
If you choose to transfer your final salary pension you will be responsible for investing your pension to provide you with an income for life.
Any investment carries risk. Investments can down as well as up and you may not get back the full amount that you invested. Which is why it is important to understand the level of risk you are going to be comfortable with.
With a Final Salary Pension scheme you are protected from market changes, and the amount you receive stays the same regardless* but one of the biggest risks of Final Salary Pension Transfer is giving up the certainty and safety found within the scheme.
With a personal pension, the amount of pension you receive will be dependent on the growth yet to be earned. It will be calculated by the size of your pension pot, when you plan to retire, how much money you plan to withdraw, and when you plan to withdraw it.
Things to consider before transferring out of your final salary pension are:
- Your attitude to risk– if uncertainty causes you anxiety and sleepless nights you may be better off remaining in the safety of the scheme.
- Your capacity for loss – if your final salary pension makes up a large proportion of your retirement income you need to consider how you’d cope if your investment went down? Could you still live comfortably if you had to survive on less?
It is always a good idea to run through your options with an Independent Financial Advisor/ Pension Specialist to ensure you are making the best decisions for your future.
* unless your scheme falls into the Pension Protection Fund, in which case 90% of your pension is guaranteed.
Stress is not something you'd expect a financial advisor to talk about with you but it's important to discuss when considering if a pension transfer is in your best interests.
There's lots of talk of multiples, high transfer values, return on investment and other financial talk but the fact remains, even if the figures adds up, if the idea of managing your own pension through retirement and dealing with investment risk causes you stress, you probably shouldn't be considering a transfer.
The Lifetime Allowance (LTA) is a limit on the value of payouts from your pension schemes that can be made without triggering an extra tax charge.
Under current tax rules, you can build up a pension fund worth £1,073,100 million over your lifetime, for both final salary and private pension owners. If the Lifetime Allowance is exceeded, an additional tax bill is payable from your pension pot.
It was reduced in 2016 and is currently set at £1,073,100. The Government has indicated that it will increase each year in line with inflation. Once you exceed this amount, you’ll pay 55% tax if you take your money as a lump sum or 25% tax if you take it as income.
How is Lifetime Allowance Calculated for Final Salary Pensions?
Lifetime allowance is calculated by your pension provider and is usually worked out on 20 times your first year’s pension plus your lump sum. This means someone with a £50,000-a-year pension income would still fall within the new £1,073,100 limit and could avoid the tax.
However, if they opt out of their pension and are offered a CETV greater than £1,073,100, they will trigger the LTA on anything paid out over that amount.
If you do exceed the LTA, your Pension Scheme Administrator will take the tax from your pension as soon as you start drawing it. The amount you receive will be reduced accordingly.
How is it worked out and payable for Defined Contribution Pensions?
For savers with defined contribution pensions, the lifetime limit is simply compared with the overall fund value.
Current tax rules allow for wealthy individuals to use Flexible Drawdown to defer the Lifetime Allowance Tax until they are 75. This can be achieved by keeping drawings within the LTA limits up to age 75 and gaining the benefit of a largely tax-exempt investment account until that date when the surcharge tax will become due on the excess value of the fund.
If you have no need for the funds in excess of the LTA then you could consider leaving these invested in your pension. Although you have to pay the LTA charge at age 75, the funds will remain outside of your estate.
You can find more information on the government website but we also recommend speaking to a Financial Adviser
Final Salary pensions come with a provision to provide a guaranteed pension for life for your surviving spouse or dependent child when you die.
This taxable pension is payable immediately after your death and is adjusted for inflation for the rest of their life or a one-off payment may be made.
If you transfer your pension then any provision for your spouse or dependent children becomes your responsibility.
If you've run your pension pot down, either through taking too much money or through poor investment performace, they'll have less money to live on, and in the worst case, may not receive anything.
Plus, they then take on the responsibility of managing their pension through retirement.
It's important to understand the true value of these associated benefits when giving up a Defined Benefit Pension.
Inflation erodes the value of money over time.
As prices for goods and services goes up, your buying power goes down. Which is fine if your income is keeping up with inflation and not so if you have a fixed income that isn't.
Final Salary Pensions have inflation protection built in. They go up in value every year to protect your money from being eroded by inflation. So the value of your pension is protected.
Personal pensions don’t have this. With a personal pension, you will be reliant on your investments outperforming inflation to protect the value of your pension.
If your investments don't keep up with inflation you could find yourself spread thinly, unable to afford the same things you once could.
Download our definitive guide to pension transfers
Discover everything you need to know about Defined Benefit Pension transfer in our expert guide
Is a pension transfer right for me?
When you transfer your Final Salary Pension you go from an investment that is guaranteed for life and protected against inflation to one that is subject to all of the risks of a standard investment. There are a number of factors that affect whether or not it might be suitable for you to transfer your final salary pension including (but not limited to):
- Your attitude to risk
- Your aptitude for risk (i.e. can you cope if your pension value goes down)
- Your age
- Your short & long-term goals
- Your investment experience
- The value of other assets/pension/wealth you hold
Can I take my final salary pension at 55?
The rules around whether you can take your Final Salary pension at 55 will be different for each scheme so you’ll need to check with your pension scheme provider first.
All final salary pension schemes have a fixed retirement age at which they will pay out but the specific age is different for each scheme. Some schemes have a protected early retirement age below 55, but most are around the 60-66 mark.
If your scheme retirement age isn’t set at 55 you’ll need to look into your options for early retirement.
Whilst some DB pension schemes allow members to take early retirement, it normally comes with stipulations:
1) Firstly, You’ll need to apply for early retirement
2) Your estimated pension income will be discounted for the fact you are retiring early
3) If you’re eligible for a cash lump sum, that will also be discounted.
Your scheme rules will depict how much your pension might be discounted by in order to reflect your early retirement. It’s important to take proper financial advice, because once you opt for early retirement, your income will be fixed at that level.
Unlike defined contribution pensions where you can access 25% of your cash as a tax-free lump sum from age 55. Final Salary pensions, normally only give you the option to take a tax-free lump sum at the same time as you take your pension.
Because of the way Final Salary Pensions work, you don’t have a specific pot of money to take 25% from, so your scheme administrators will calculate how much you’ll get based on their own workings.
What you are offered may not be equal to the 25% you might receive if your pension was in a defined contribution arrangement.
Early retirement is calculated differently for each pension scheme, so it’s important to contact your scheme administrator to find out what rules apply to you. More importantly, you should seek expert guidance to see if it’s in your best interests.
Specialist pension transfer advice
Our Independent pension transfer advice is designed to help you meet your goals in the best way for you, whether that’s exploring your options within your scheme or moving your pension to a defined contribution arrangement.

TRANSFER ANALYSIS
First we start with understanding you and where you want to be.
We’ll discuss your goals, talk about the risks and benefits of pension transfer and carry out a detailed fact-find and analysis to see if transferring is really in your best interests.

REPORT & RECOMMENDATIONS
You'll receive an in-depth report that assesses your suitability to transfer based on your goals, risk assessment and your personal and financial situation.
You'll receive suggestions for alternative courses of action & our expert recommendation.

MANAGE & REVIEW
If appropriate and if you decide to go ahead with transferring your pension, we will seamlessly manage your transfer to your recommended arrangement, offer regular portfolio rebalancing and provide ongoing advice & support to ensure you stay on track.
Frequently Asked Questions

Download our definitive guide to pension transfers
Discover everything you need to know about Defined Benefit Pension transfer in our expert guide
Don't miss
Our most popular posts
These are some of our most popular posts. Click below or head over to our blog to see other helpful articles on pensions, retirement and investing.